Case Study: Morgan Parks – Company Director saves 49%
No pressure, no jargon. A short call to work out whether this cover fits your business.
We recently worked with Morgan Parks recruitment. The Director was paying personal private insurance policies at the cost of over £129 a month.
Current policy
- Level 25 years term insurance policy for the cover of £300,000
- Life and critical illness cover
- Premiums £129 a month
The main challenge we had with this policy was replacing the critical illness cover. Relevant life cover does not allow full critical illness cover to be included as HMRC won’t allow this. Therefore, we needed to find a Relevant Life provider that would also off some serious illness cover.
Serious illness cover is allowable by HMRC and is essentially a watered-down version of the critical illness. Most of the major conditions are still covered. However, some of the more minor conditions are excluded. For example, the loss of your sight would not be classed as a serious illness. However, it would have been classed as a critical illness.
Results
After researching the entire market, we concluded that Aviva would be the best provider, offering serious illness cover and at a competitive rate.
New Policy:
- Level 22-year term insurance for £300,000
- Life and serious illness cover
- Premiums £105 a month
- Total premium saving of £6,336 over the life of the contract.
As the premiums are now being paid through the company, a further tax saving can be made.
If this new policy of £105 a month was paid from the Director’s personal income, it would have required a gross income of £166.87. After income tax, employees and employer national insurance is deducted this would leave the £105 needed to pay the premium as a personal expense.
Opting to pay the policy as a business expense instead would make a saving of £81.82 a month, and after taking into account the corporation tax saving as well, the cost to the business is just £85.05.
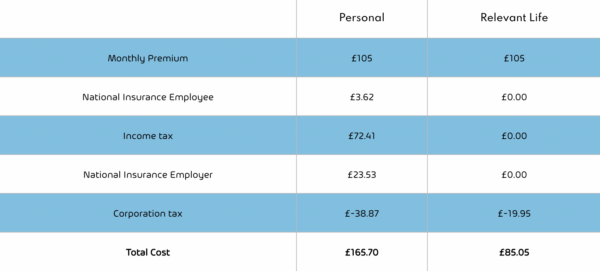
This is a 49% saving for the same policy, on a like for like basis, by simply paying the premium as a company expense.
Now, although these figures sound small, over the course of the contract, they make a massive difference, £21,600.48 to be exact.
Both of these savings, £6,336 in premium reductions and £21,600.48 in tax savings ad up to a massive saving of £27,936.48.
Written by
Alex Ogden DipFA | Director | Executive Life
Alex Ogden DipFA holds the Level 4 Diploma for Financial Advisers (DipFA) awarded by the Walbrook Institute London, formerly known as the London Institute of Banking & Finance (LIBF), the FCA's benchmark qualification for retail investment advisers. He is authorised by the FCA, Ref: AJO01072. View the FCA register entry.
Tax rates and thresholds are subject to change.