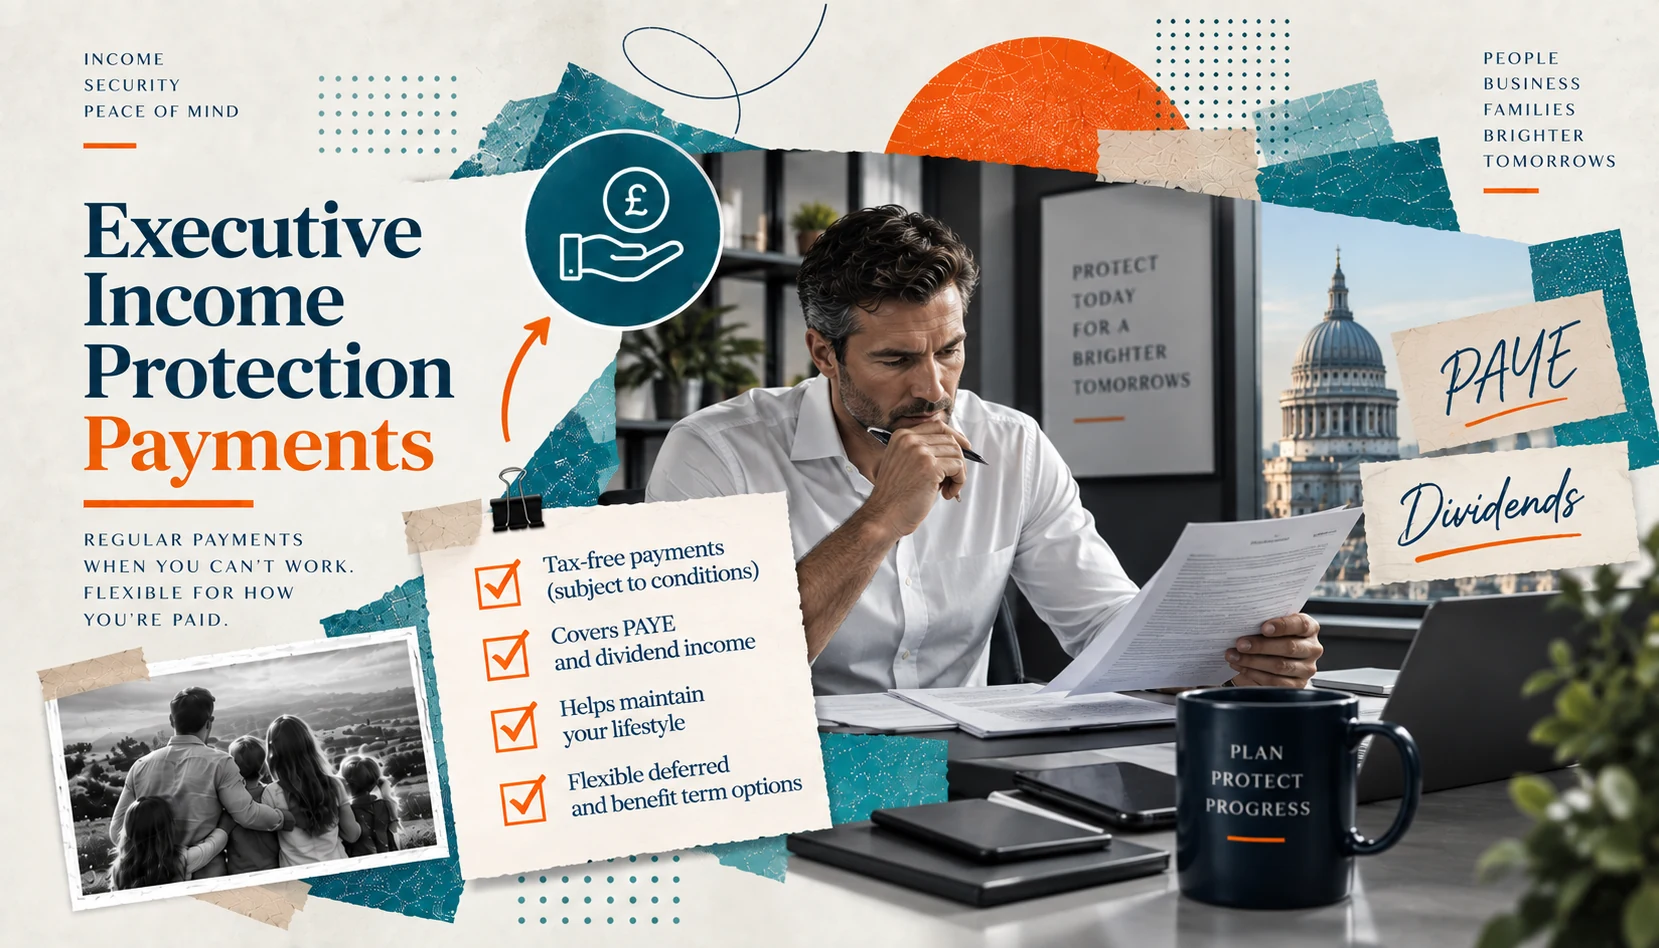
Is Executive Income Protection Taxable? Why the Payout Is Drawn as PAYE, Not Dividends
No pressure, no jargon. A short call to work out whether this cover fits your business.
An executive income protection payout is taxable, and it is almost always drawn by the director as PAYE salary rather than as a dividend. That's because the business receives the claim as taxable income, and paying it out as salary is the only route that gives the company corporation tax relief on the money and guarantees the director can draw it, whether or not the business turns a profit that year.
So is income protection a taxable benefit in this context? The answer is yes - the claim the business receives is taxable, and so is the amount the director ultimately draws from it, because that amount is paid through PAYE rather than as a tax-free lump sum to the individual.
Key Facts
- When an executive income protection claim pays out, the money goes to the business first, and is treated as taxable income for the company.
- The director then draws the benefit as PAYE salary, taxed through income tax and Class 1 National Insurance like ordinary earnings.
- Paying the benefit as salary lets the company claim corporation tax relief on the amount paid out, offsetting the tax on the claim it received.
- A dividend does not qualify for that relief, since dividends are paid from post-tax profit rather than as a deductible expense.
- A dividend also depends on the company having distributable reserves, so it isn't a guaranteed route if the business isn't otherwise profitable.
- PAYE salary is a contractual entitlement, so it can be paid regardless of the company's wider trading position that year.
Is executive income protection taxable, and how is the payout taxed?
When a claim is accepted, the insurer pays the benefit to the business, not directly to the director, since the company is the policyholder. That payment is treated as taxable trading income for the business. The company then pays the director, and it's this second step, how the business gets the money to the director, that decides the overall tax outcome. The income protection payout tax outcome therefore turns on this second step, not on whether the initial claim itself is taxable.
Does the tax treatment change if the claim runs for several years?
No. Executive income protection often pays out monthly for the length of a claim rather than as a single lump sum, but the tax mechanics stay the same for every payment: the insurer pays the business, the business treats it as taxable income, and the director draws each instalment as PAYE salary.
Why is executive income protection taxable as PAYE salary rather than as a dividend?
Salary is a deductible business expense, so when the company pays the director via PAYE, it can claim corporation tax relief on that payment, broadly offsetting the tax due on the claim it received. A dividend doesn't work the same way: dividends are distributed from profit that has already been taxed, so there's no equivalent deduction, and the company would be left carrying the tax cost on the claim with nothing to offset it against.
Why does PAYE guarantee the payment when dividends don't?
A dividend can only be paid if the company has distributable reserves and the directors formally declare it, a genuine problem if the business has struggled while the director has been off sick, since profits and dividend headroom can fall away exactly when the money is needed most. PAYE salary doesn't have that constraint. It's a contractual obligation to the director for their role, funded directly by the claim proceeds the company has just received, so it doesn't depend on the business having made a profit that year.
Does this affect dividends the director takes for other reasons?
No. This tax treatment applies only to the specific amount funded by the income protection claim. It doesn't change how the director is normally remunerated, and dividends taken from ordinary trading profit in the same year are unaffected.
What does this mean for corporation tax overall?
Taken together, the two sides broadly net off: the company pays corporation tax on the claim it receives, then gets corporation tax relief on the salary it pays the director, provided that payment meets HMRC's wholly and exclusively rules for a genuine business expense. This is the same mechanism that lets the premium qualify for relief in the first place, just running in reverse on the way out.
What tax does the director pay personally on the payout?
As PAYE salary, the payout is taxed at the director's normal marginal rate of income tax, the same basic, higher, or additional rate bands that apply to any other earnings, and it also carries Class 1 employee National Insurance. That's a different tax treatment to a dividend, which is taxed at the dividend rates of 10.75%, 35.75%, or 39.35% for the 2026/27 tax year, with no National Insurance charge, but without the corporation tax relief or the payment guarantee that come with PAYE.
The table below summarises this executive income protection PAYE vs dividend comparison in full.
Frequently asked questions
Is an executive income protection payout taxable?
Yes. The claim is paid to the business as taxable income, and the director then draws it as PAYE salary, which is taxed as normal employment income through income tax and Class 1 National Insurance, in the same way as any other salary payment.
Why is the payout usually taken as PAYE salary rather than dividends?
Salary is a deductible business expense, so paying the director via PAYE gives the company corporation tax relief on the amount paid out, roughly offsetting the tax on the claim it received. A dividend isn't deductible, so the company would be left with an unrelieved tax cost, and the payment would depend on the business having distributable profit.
Does the company pay corporation tax on the claim it receives?
Yes, the claim proceeds are treated as taxable income for the business. This is the reverse side of the premium qualifying for corporation tax relief in the first place. Paying the money out as salary provides a matching deduction that offsets this.
Can the payout still be taken as a dividend instead of PAYE?
It's possible if the company has sufficient distributable reserves, but it's rarely advisable. The company loses the corporation tax relief it would have had on a salary payment, and the payment is no longer guaranteed if the business isn't otherwise profitable that year.
Does the director pay National Insurance on the payout?
Yes. Because the payout is drawn as PAYE salary, it's subject to Class 1 employee National Insurance in the same way as ordinary earnings, in addition to income tax at the director's marginal rate, with both deducted automatically through the payroll each time a payment is made.
This article is for information purposes only and does not constitute financial advice. It states specific corporation tax, income tax, and National Insurance positions, and tax rates and thresholds are subject to change. Always seek professional advice before making financial decisions.
Written by
Alex Ogden DipFA | Director | Executive Life
Alex Ogden DipFA holds the Level 4 Diploma for Financial Advisers (DipFA) awarded by the Walbrook Institute London, formerly known as the London Institute of Banking & Finance (LIBF), the FCA's benchmark qualification for retail investment advisers. He is authorised by the FCA, Ref: AJO01072. View the FCA register entry.
Tax rates and thresholds are subject to change.