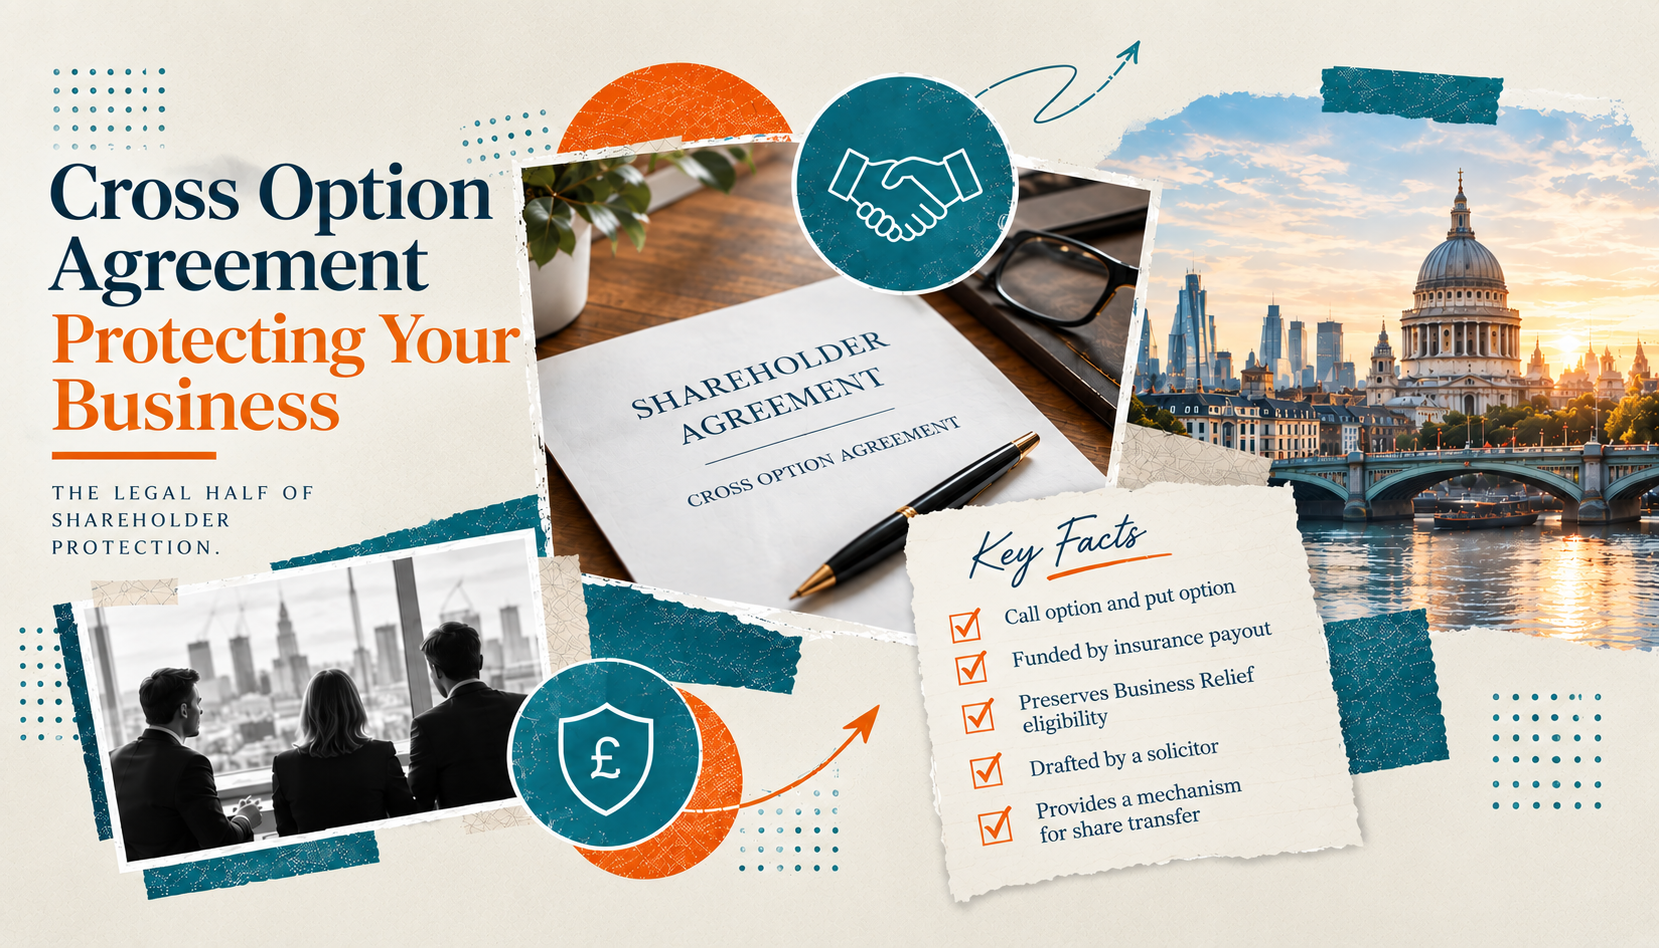
Cross Option Agreements Explained: How They Protect Your Business
No pressure, no jargon. A short call to work out whether this cover fits your business.
A cross option agreement is a legal arrangement giving surviving shareholders the option to buy a deceased shareholder's shares, and giving the deceased's estate the option to sell them, with the purchase typically funded by a shareholder protection insurance payout. It is the legal half of a shareholder protection arrangement — the document that turns an insurance payout into an orderly transfer of ownership.
Key facts
- A cross option agreement gives surviving shareholders a call option to buy, and the deceased's estate a put option to sell, the deceased's shares.
- It is typically funded by a shareholder protection insurance payout, written under trust.
- Cross option agreements are generally preferred over binding buy-sell agreements because a binding sale obligation can affect eligibility for Business Relief.
- A solicitor usually drafts the agreement, working alongside the business's insurance adviser.
- Without this agreement, a shareholder protection insurance payout has no automatic mechanism for transferring the shares.
How a Cross Option Agreement Works
The agreement sits alongside, not instead of, the insurance policies. On the death of a shareholder, the insurer pays the sum assured to the trust. The cross option agreement then governs what happens next: it gives both sides - the surviving shareholders and the deceased's estate - a defined right to require the share transfer to go ahead at an agreed or formula-based valuation.
The Call Option and the Put Option
A call option gives the surviving shareholders the right to buy the deceased's shares if they choose to exercise it. A put option gives the deceased's personal representatives the right to require the surviving shareholders to buy those shares. Crucially, neither side is automatically obliged to act. The agreement sets out options, not a binding sale, until one party exercises their option. Once exercised, the other side is bound to complete.
Why Cross Option Agreements (Not Binding Buy-Sell Agreements)?
It would seem simpler to draft a binding agreement that says the shares must be sold and bought automatically on death. In practice, this structure can create a problem with Business Relief - the inheritance tax relief that applies to qualifying business assets such as shares in a trading company.
HMRC can treat a binding obligation to sell as effectively converting the shares into a right to receive cash rather than a genuine interest in a business, which may put Business Relief eligibility at risk. A cross option structure, where each side holds an option rather than a binding commitment, is generally considered to preserve the shares' qualifying status until an option is actually exercised. This is a nuanced area and individual circumstances vary, so specialist legal and tax advice should always be taken when structuring an agreement. See HMRC's guidance on Business Relief for Inheritance Tax for the underlying rules.
Cross Option Agreement vs Binding Buy-Sell Agreement
| Cross option agreement | Binding buy-sell agreement | |
|---|---|---|
| Structure | Each side holds an option, not an obligation, until exercised | Sale is contractually required to happen automatically |
| Business Relief impact | Generally considered to preserve eligibility, subject to individual circumstances | May be treated as converting shares into a right to cash, risking eligibility |
| Flexibility | Either side can choose whether to exercise their option | Little flexibility once triggered |
| Common usage | Standard approach used alongside shareholder protection insurance | Less commonly recommended for this reason |
What Should a Cross Option Agreement Include?
A properly drafted agreement should cover who the parties are, the events that trigger the options (typically death, and often critical illness if that cover is also in place), the time period within which an option must be exercised, and how the share valuation will be determined, whether by a fixed formula, an independent valuer, or another agreed method.
- The parties to the agreement and the shares each holds
- The trigger events that activate the call and put options
- The exercise period within which an option must be used
- The valuation method for the shares
- How the agreement interacts with the insurance policies and trust arrangements
Setting Up a Cross Option Agreement: Who's Involved?
A solicitor sometimes drafts the cross-option agreement, working alongside the business's insurance adviser to ensure it aligns correctly with the shareholder protection insurance policies in place. Here at Executive Life, we also offer a templated version for simpler cases and can talk businesses through the details. Our role is to make sure the sum assured on each policy genuinely matches the share value the agreement is built around, and that the trust arrangements support the mechanism the solicitor has drafted. Working as a team is what makes the arrangement function as intended.
If your business has shareholder protection insurance in place, or is considering it, and does not yet have a cross option agreement to go with it, it is worth speaking to us about shareholder protection to get the legal and insurance elements aligned.
Last reviewed: June 2026 — Next review: April 2027. Tax rates and thresholds are subject to change. This article will be updated following each HMRC Autumn Budget or Spring Statement where relevant thresholds change.
Frequently Asked Questions About Cross Option Agreements
What is a cross option agreement?
A cross option agreement is a legal arrangement giving surviving shareholders the option to buy a deceased shareholder's shares, and giving the deceased's estate the option to sell them, with the purchase typically funded by a shareholder protection insurance payout.
Why not just use a binding buy-sell agreement?
A binding buy-sell agreement can affect eligibility for Business Relief - the inheritance tax relief on qualifying business assets - because it may be treated as a contract for sale rather than a genuine inheritance. A cross option agreement preserves optionality and is generally the preferred structure for this reason, though individual circumstances vary and specialist advice should be taken.
Who drafts a cross option agreement?
A solicitor typically drafts the agreement, working alongside the business's insurance adviser to ensure it aligns correctly with the shareholder protection insurance policies in place.
Do you need a cross option agreement with shareholder protection insurance?
Yes, a shareholder protection insurance payout provides the funds, but without a cross option agreement there is no automatic legal mechanism to transfer the shares to the surviving shareholders. The two elements work together: insurance provides the cash, the cross option agreement governs how it is used.
What is the difference between a call option and a put option in a cross option agreement?
A call option gives the surviving shareholders the right to buy the deceased's shares if they choose to exercise it. A put option gives the deceased's personal representatives the right to require the surviving shareholders to buy those shares. Neither side is automatically obliged to act. The agreement sets out options, not a binding sale, until one party exercises their option.
Written by
Alex Ogden DipFA | Director | Executive Life
Alex Ogden DipFA holds the Level 4 Diploma for Financial Advisers (DipFA) awarded by the London Institute of Banking and Finance (LIBF). He is authorised by the FCA, Ref: AJO01072. View the FCA register entry.
This article is for general information only and does not constitute financial, tax or legal advice. Tax treatment depends on individual circumstances and may change in future. Executive Life is authorised and regulated by the Financial Conduct Authority. Speak to a qualified adviser before making any decisions based on this content.